๋ณธ๋ฌธ์œผ๋กœ ๊ฑด๋„ˆ๋›ฐ๊ธฐ
-
Subscribe to our newsletter & never miss our best posts. Subscribe Now!
ACADEMICUS
ACADEMICUS
  • About
    • Notice(๊ณต์ง€)
    • Q&A(์งˆ์˜์‘๋‹ต)
    • ACADEMICUS CAMPUS
  • Articles
    • Report
    • Research(์—ฐ๊ตฌ)
      • Reference(์ฐธ๊ณ ์ž๋ฃŒ)
      • Research Journal(์—ฐ๊ตฌ์ผ์ง€)
        • SH๋„์‹œ์—ฐ๊ตฌ์›(2022)
        • Paper Competition(๊ณต๋ชจ์ „)
          • ๊ณต๋ชจ์ „(2022)
          • ๊ณต๋ชจ์ „(2024)
          • ๊ณต๋ชจ์ „(2026)
        • ์‹ ์ง„์—ฐ๊ตฌ์ง€์›์‚ฌ์—…(2026-2029)
          • ์‹ ์ง„์—ฐ๊ตฌ์ง€์›์‚ฌ์—…(2026)
      • Research Report(์—ฐ๊ตฌ ๋ณด๊ณ ์„œ)
    • Languages(์–ดํ•™)
      • TOEIC
      • G-TELP
    • Certificate(์ž๊ฒฉ์ฆ)
      • IT/OA
      • ์žฌ๊ฒฝ๊ด€๋ฆฌ์‚ฌ
      • ๊ธฐ์—…/์„ธ๋ฌดํšŒ๊ณ„
      • ์ „์‚ฐํšŒ๊ณ„์šด์šฉ์‚ฌ
      • ERP ์ •๋ณด๊ด€๋ฆฌ์‚ฌ
      • ์ „์‚ฐ์„ธ๋ฌดํšŒ๊ณ„/AT
      • Tax Accountant(์„ธ๋ฌด์‚ฌ)
        • First examination(1์ฐจ ์‹œํ—˜)
          • Tax law(์„ธ๋ฒ•)
          • Finance(์žฌ์ •ํ•™)
          • Financial accounting(์žฌ๋ฌดํšŒ๊ณ„)
          • Administration Litigation Act(ํ–‰์ •์†Œ์†ก๋ฒ•)
          • Cost management accounting(์›๊ฐ€๊ด€๋ฆฌํšŒ๊ณ„)
        • Final examination(2์ฐจ ์‹œํ—˜)
      • Social Worker(์‚ฌํšŒ๋ณต์ง€์‚ฌ)
    • Field of study(ํ•™๋ฌธ)
      • Tax Law(์กฐ์„ธ๋ฒ•ํ•™)
        • Income Tax(์†Œ๋“์„ธ)
        • Corporate Income Tax(๋ฒ•์ธ์„ธ)
        • Value-Added Tax(๋ถ€๊ฐ€๊ฐ€์น˜์„ธ)
        • Inheritance and Gift Tax Act(์ƒ์†์„ธ ๋ฐ ์ฆ์—ฌ์„ธ๋ฒ•)
        • Restriction of Special Taxation Act(์กฐ์„ธํŠน๋ก€์ œํ•œ๋ฒ•)
        • Framework Act on National Taxes(๊ตญ์„ธ๊ธฐ๋ณธ๋ฒ•)
        • National Tax Collection Act(๊ตญ์„ธ์ง•์ˆ˜๋ฒ•)
        • Local Tax Act(์ง€๋ฐฉ์„ธ๋ฒ•)
        • Comprehensive Real Estate Holding Tax(์ข…ํ•ฉ๋ถ€๋™์‚ฐ์„ธ)
        • Individual Consumption Tax(๊ฐœ๋ณ„์†Œ๋น„์„ธ)
        • Securities Transaction Tax(์ฆ๊ถŒ๊ฑฐ๋ž˜์„ธ)
        • Customs Duty(๊ด€์„ธ)
      • Tax Accounting(์„ธ๋ฌดํšŒ๊ณ„ํ•™)
      • Tax Psychology(์กฐ์„ธ์‹ฌ๋ฆฌํ•™)
    • Practical Work(์‹ค๋ฌด)
      • Tax(์„ธ๋ฌด)
      • Architecture(๊ฑด์ถ•)
  • Review
    • Book(๋„์„œ)
    • Seminar(๊ฐ•์—ฐ/์„ธ๋ฏธ๋‚˜)
    • Paper/Report(๋…ผ๋ฌธ/๋ณด๊ณ ์„œ)
  • Disscussions
  • Resources
    • Form(์–‘์‹)
  • NEWSCUS(AI)
    • Tax issue(์กฐ์„ธ ์ด์Šˆ)
    • Social issue(์‚ฌํšŒ ์ด์Šˆ)
    • Welfare issue(๋ณต์ง€ ์ด์Šˆ)
๋‹ซ๊ธฐ

๊ฒ€์ƒ‰

  • https://www.facebook.com/
  • https://twitter.com/
  • https://t.me/
  • https://www.instagram.com/
  • https://youtube.com/
Subscribe
Tax issue(์กฐ์„ธ ์ด์Šˆ)

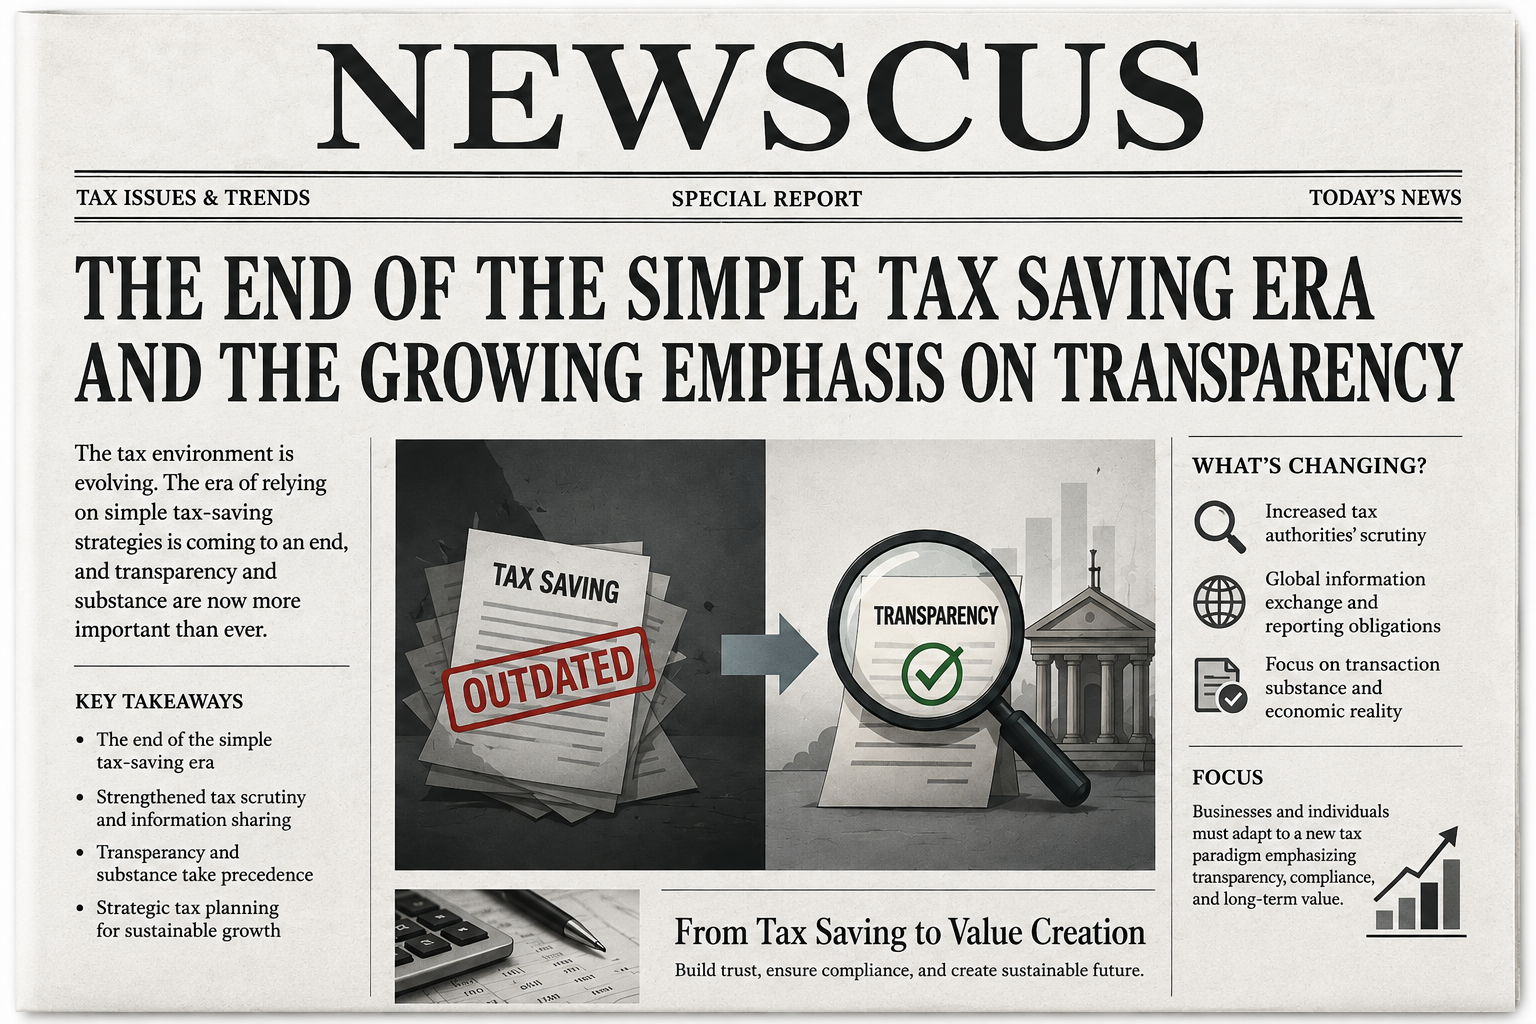
๐Ÿ“ฐ NEWSCUS: Tax Issues & Trends(์กฐ์„ธ์ด์Šˆ&ํŠธ๋ Œ๋“œ) – The end of the simple tax-saving era, and the growing emphasis on transparency, fairness, and digital taxation(๋‹จ์ˆœ ์ ˆ์„ธ ์‹œ๋Œ€ ์ข…๋ฃŒ์™€ ํˆฌ๋ช…์„ฑ, ๊ณต์ •์„ฑ, ๋””์ง€ํ„ธ ๊ณผ์„ธ ๊ฐ•ํ™”)

By academicus
2026-06-22 5 Min Read
0

6์›” ๋„ท์งธ์ฃผ ์กฐ์„ธ ์ด์Šˆ ๋ฐ ํŠธ๋ Œ๋“œ (๊ตญ๋‚ดยทํ•ด์™ธ ์ข…ํ•ฉ)

๐Ÿ“Œ Domestic Tax Issues (Korea)(๊ตญ๋‚ด ์กฐ์„ธ ์ด์Šˆ)

๐Ÿ‘‰ โ€œExpansion of deductions + strengthening of taxationโ€(โ€œ๊ณต์ œ ํ™•๋Œ€ + ๊ณผ์„ธ ๊ฐ•ํ™”โ€) โ†’ A restructuring of the tax system centered on the middle class.(์ค‘์‚ฐ์ธต ์ค‘์‹ฌ ์„ธ์ œ ์žฌํŽธ)

1. Strengthening the Link Between Tax Revenue and the Real Estate Market(์„ธ์ˆ˜ยท๋ถ€๋™์‚ฐ ์—ฐ๋™ ๊ตฌ์กฐ ๊ฐ•ํ™”)

  • In Seoul, increased tax revenue has led to improved fiscal capacity.(์„œ์šธ์‹œ ๊ธฐ์ค€, ์„ธ์ˆ˜ ์ฆ๊ฐ€๋กœ ์žฌ์ • ์—ฌ๋ ฅ ํ™•๋Œ€ ํ™•์ธ)
  • Rising real estate prices and increased transaction volumes have recently boosted local tax revenues, particularly acquisition taxes.(์ตœ๊ทผ ๋ถ€๋™์‚ฐ ๊ฐ€๊ฒฉ ์ƒ์Šน + ๊ฑฐ๋ž˜ ์ฆ๊ฐ€๋กœ ์ง€๋ฐฉ์„ธ(ํŠนํžˆ ์ทจ๋“์„ธ) ์ˆ˜์ž… ์ฆ๊ฐ€)

โ†’ Key Points(ํ•ต์‹ฌ ํฌ์ธํŠธ)

  • Tax revenue is closely linked to economic conditions and asset markets.(์„ธ์ˆ˜๋Š” ๊ฒฝ๊ธฐยท์ž์‚ฐ์‹œ์žฅ๊ณผ ๊ฐ•ํ•˜๊ฒŒ ์—ฐ๋™)
  • Changes in real estate policy directly impact tax revenue.(๋ถ€๋™์‚ฐ ์ •์ฑ… ๋ณ€ํ™” โ†’ ๊ณง๋ฐ”๋กœ ์„ธ์ˆ˜ ์˜ํ–ฅ)

โ†’ Implications(์‹œ์‚ฌ์ )

  • Future changes in real estate regulationsโ€”whether eased or tightenedโ€”may significantly affect the stability of local government finances.(ํ–ฅํ›„ ๋ถ€๋™์‚ฐ ๊ทœ์ œ ์™„ํ™” vs ๊ฐ•ํ™”์— ๋”ฐ๋ผ ์ง€๋ฐฉ์žฌ์ • ์•ˆ์ •์„ฑ๋„ ๋ณ€๋™ ๊ฐ€๋Šฅ)

2. Trend Toward Strengthening Gift Tax Enforcement(์ฆ์—ฌ์„ธ ๊ณผ์„ธ ๊ฐ•ํ™” ํŠธ๋ Œ๋“œ)

  • Even the use of parentsโ€™ credit cards or financial support for living expenses can be treated as a taxable gift when it leads to asset accumulation.(๋ถ€๋ชจ ์นด๋“œ ์‚ฌ์šฉ, ์ƒํ™œ๋น„ ์ง€์›๋„ ์ž์‚ฐ ์ถ•์  ์‹œ ์‚ฌ์‹ค์ƒ ์ฆ์—ฌ๋กœ ๊ณผ์„ธ ๊ฐ€๋Šฅ)

โ†’ Key Points(ํ•ต์‹ฌ ํฌ์ธํŠธ)

  • The principle of ‘substance over form’ in taxation is being reinforced.(โ€˜ํ˜•์‹๋ณด๋‹ค ์‹ค์งˆโ€™ ๊ณผ์„ธ ์›์น™ ๊ฐ•ํ™”)
  • Everyday transfers of funds are increasingly becoming subject to taxation.(์ผ์ƒ์  ์ž๊ธˆ ์ด์ „๋„ ๊ณผ์„ธ ๋Œ€์ƒ ํ™•๋Œ€)

โ†’ Implications(์‹œ์‚ฌ์ )

  • As financial activities among younger individuals increase, the risk of gift tax exposure is also rising.(์ž๋…€ ๊ธˆ์œต ํ™œ๋™ ์ฆ๊ฐ€ โ†’ ์ฆ์—ฌ์„ธ ๋ฆฌ์Šคํฌ ํ™•๋Œ€)
  • The importance of tax management is growing, particularly for people in their 20s and 30s.(์„ธ๋ฌด๊ด€๋ฆฌ ์ค‘์š”์„ฑ ์ƒ์Šน (ํŠนํžˆ 20~30๋Œ€))

3. ์„ธ์ œ ํ˜œํƒ ์ถ•์†Œ ํ๋ฆ„

  • ์ „๊ธฐ์ฐจ ๊ฐœ๋ณ„์†Œ๋น„์„ธ ๊ฐ๋ฉด ํ์ง€ ๊ฒ€ํ†  ๋“ฑ ์ •์ฑ…์„ฑ ์„ธ์ œํ˜œํƒ ์ ์ง„์  ์ •๋ฆฌ

โ†’ Key Points(ํ•ต์‹ฌ ํฌ์ธํŠธ)

  • ์ •๋ถ€ ์žฌ์ • ํ™•๋ณด vs ์‚ฐ์—… ์ง€์›์˜ ๊ท ํ˜•
  • ์„ธ์ œ ๋Œ€์‹  ์ง์ ‘ ๋ณด์กฐ๊ธˆ ๋ฐฉ์‹ ์ „ํ™˜

โ†’ Implications(์‹œ์‚ฌ์ )

  • ์„ธ๊ธˆ ํ• ์ธ๋ณด๋‹ค โ€œํ˜„๊ธˆ์ง€์› ์ •์ฑ…โ€ ํ™•๋Œ€ ๊ฐ€๋Šฅ
  • ์†Œ๋น„์ž ์ฒด๊ฐ ๋ถ€๋‹ด์€ ์ฆ๊ฐ€ํ•  ์ˆ˜ ์žˆ์Œ

๐Ÿ“Š Key Trends in Inheritance & Gift Tax(์ƒ์†ยท์ฆ์—ฌ์„ธ ํ•ต์‹ฌ ํŠธ๋ Œ๋“œ)

1. Inheritance Tax Reform(์ƒ์†์„ธ ๊ฐœํŽธ): โ€œShifting from Tax Rates to Deduction Structuresโ€
(โ€œ์„ธ์œจ๋ณด๋‹ค ๊ณต์ œ ๊ตฌ์กฐ ๋ณ€ํ™”โ€)

  • Key discussions focus on expanding child-related deductions and increasing the basic lump-sum deduction.(์ž๋…€ ๊ณต์ œ ํ™•๋Œ€, ์ผ๊ด„๊ณต์ œ ์ƒํ–ฅ ๋“ฑ์ด ํ•ต์‹ฌ ๋…ผ์˜)
  • There is also ongoing debate about lowering the top tax rate (from 50% to 40%).(์ตœ๊ณ ์„ธ์œจ ์ธํ•˜(50% โ†’ 40%) ๋ฐฉํ–ฅ ์ง€์† ๋…ผ์˜)

โ†’ Key Points(ํ•ต์‹ฌ ํฌ์ธํŠธ)

  • A shift toward expanded deductions is easing the tax burden on the middle class.(๊ณต์ œ ํ™•๋Œ€ ์ค‘์‹ฌ โ†’ ์ค‘์‚ฐ์ธต ์„ธ๋ถ€๋‹ด ์™„ํ™”)
  • The number of taxpayers subject to inheritance tax may decrease.(์ƒ์†์„ธ ๋Œ€์ƒ ์ž์ฒด ๊ฐ์†Œ ๊ฐ€๋Šฅ)

โ†’ Implications(์‹œ์‚ฌ์ )

  • Inheritance tax is no longer limited to high-net-worth individuals and is becoming a broader issue affecting general households.(์ž์‚ฐ๊ฐ€๋งŒ์˜ ์„ธ๊ธˆ โ†’ ์ผ๋ฐ˜ ๊ฐ€๊ตฌ ์ด์Šˆ๋กœ ํ™•๋Œ€)
  • Tax planning strategies(์ ˆ์„ธ ์ „๋žต):
    • Choosing between gifting and inheritance is becoming more important.(์ฆ์—ฌ vs ์ƒ์† ์„ ํƒ ์ค‘์š”ํ•ด์ง)
    • The number of children has emerged as a key variable in determining the scale of deductions.(โ€œ์ž๋…€ ์ˆ˜ = ๊ณต์ œ ๊ทœ๋ชจโ€ ํ•ต์‹ฌ ๋ณ€์ˆ˜)

2. Transition from Estate Tax(์œ ์‚ฐ์„ธ) โ†’ Inheritance Acquisition Tax(์œ ์‚ฐ์ทจ๋“์„ธ ์ „ํ™˜ ๋…ผ์˜)

  • Currently(ํ˜„์žฌ): Taxed based on the total estate.(์ „์ฒด ์œ ์‚ฐ ๊ธฐ์ค€ ๊ณผ์„ธ)
  • In the future(ํ–ฅํ›„): A shift toward taxation based on each heirโ€™s share is being considered (target: 2028).(์ƒ์†์ธ๋ณ„ ๊ณผ์„ธ ๋ฐฉ์‹ ์ „ํ™˜ ๊ฒ€ํ†  (2028 ๋ชฉํ‘œ))

โ†’ Key Points(ํ•ต์‹ฌ ํฌ์ธํŠธ)

  • Improves tax fairness by taxing individuals based on what they actually receive.(๊ณผ์„ธ ํ˜•ํ‰์„ฑ ๊ฐœ์„  (๊ฐ์ž ๋ฐ›์€ ๋งŒํผ ๊ณผ์„ธ))
  • Aligns with international standards followed by many OECD countries.(๊ตญ์ œ ๊ธฐ์ค€(OECD ๋‹ค์ˆ˜ ๊ตญ๊ฐ€)๊ณผ ์ •๋ ฌ)

โ†’ Implications(์‹œ์‚ฌ์ )

  • Tax burdens may vary more depending on family structure.(๊ฐ€์กฑ ๊ตฌ์กฐ์— ๋”ฐ๋ผ ์„ธ๊ธˆ ์ฐจ์ด ํ™•๋Œ€)
  • The importance of inheritance planning is expected to increase.(์ƒ์† ํ”Œ๋žœ ์„ค๊ณ„ ์ค‘์š”์„ฑ โ†‘)

๐ŸŒ Global Tax Issues(ํ•ด์™ธ ์กฐ์„ธ ์ด์Šˆ)

๐Ÿ‘‰ โ€œMinimum tax rates(์ตœ์ €์„ธ์œจ) + standardized rules(๊ทœ์ • ํ†ต์ผ)โ€ โ†’ A shift from tax competition to regulatory competition(์กฐ์„ธ ๊ฒฝ์Ÿ โ†’ ๊ทœ์ œ ๊ฒฝ์Ÿ ์ „ํ™˜)

1. Full Implementation of the Global Minimum Tax (Pillar Two)(๊ธ€๋กœ๋ฒŒ ์ตœ์ €ํ•œ์„ธ(Pillar 2) ๋ณธ๊ฒฉ ์‹œํ–‰)

  • A minimum corporate tax rate of 15% is applied to multinational enterprises.(๋‹ค๊ตญ์ ๊ธฐ์—… ๋Œ€์ƒ ์ตœ์†Œ ๋ฒ•์ธ์„ธ์œจ 15% ์ ์šฉ)
  • In 2026, the system enters the actual reporting and operational phase.(2026๋…„: ์‹ค์ œ ์‹ ๊ณ ยท์šด์˜ ๋‹จ๊ณ„ ์ง„์ž…)

โ†’ Key Points(ํ•ต์‹ฌ ํฌ์ธํŠธ)

  • Prevents tax avoidance (addressing base erosion).(์กฐ์„ธํšŒํ”ผ ๋ฐฉ์ง€ (Base Erosion ๋Œ€์‘))
  • Approximately 140 countries are participating.(์•ฝ 140๊ฐœ๊ตญ ์ฐธ์—ฌ)

โ†’ Implications(์‹œ์‚ฌ์ )

  • For global corporations(๊ธ€๋กœ๋ฒŒ ๊ธฐ์—…):
    • Tax strategy is shifting from โ€œtax minimizationโ€ to โ€œregulatory compliance.โ€(์„ธ๊ธˆ ์ „๋žต โ†’ โ€œ์ ˆ์„ธ โ†’ ๊ทœ์ • ์ค€์ˆ˜โ€๋กœ ์ „ํ™˜)
  • For governments(๊ตญ๊ฐ€):
    • Corporate tax competitiveness is becoming less about tax rates and more about policy stability and regulatory certainty.(๋ฒ•์ธ์„ธ ๊ฒฝ์Ÿ๋ ฅ โ†’ ์„ธ์œจ๋ณด๋‹ค ์ œ๋„ ์•ˆ์ •์„ฑ ์ค‘์š”)

2. Enhancements to the OECD Pillar Two Framework(OECD Pillar 2 ์ œ๋„ ๋ณด์™„)

  • The introduction of a Side-by-Side system helps prevent double taxation.(๋ณ‘ํ–‰์ฒด๊ณ„(Side-by-Side) ๋„์ž… โ†’ ์ด์ค‘๊ณผ์„ธ ๋ฐฉ์ง€)
  • There is also expanded recognition of tax incentives for real economic investments.(์‹ค๋ฌผํˆฌ์ž ์„ธ์ œ ์ธ์„ผํ‹ฐ๋ธŒ ์ธ์ • ํ™•๋Œ€)

โ†’ Key Points(ํ•ต์‹ฌ ํฌ์ธํŠธ)

  • A balance between investment promotion and stronger taxation.(โ€œํˆฌ์ž์œ ๋„ vs ๊ณผ์„ธ๊ฐ•ํ™”โ€ ๊ท ํ˜•)
  • Measures are included to ease the burden on businesses.(๊ธฐ์—… ๋ถ€๋‹ด ์™„ํ™” ์žฅ์น˜ ํฌํ•จ)

โ†’ Implications(์‹œ์‚ฌ์ )

  • Favorable conditions for companies engaged in R&D and capital investments.(R&Dยท์„ค๋น„ ํˆฌ์ž ๊ธฐ์—…์— ์œ ๋ฆฌ)
  • Competition among countries to attract investment is expected to continue.(๊ตญ๊ฐ€ ๊ฐ„ ํˆฌ์ž ์œ ์น˜ ๊ฒฝ์Ÿ์€ ๊ณ„์† ์œ ์ง€)

3. Global Tax Environment(๊ธ€๋กœ๋ฒŒ ์„ธ๋ฌด ํ™˜๊ฒฝ): โ€œIncreasing Complexity(๋ณต์žก์„ฑ ์ฆ๊ฐ€)โ€

  • 84% of companies expect greater tax disclosure requirements in the future.(๊ธฐ์—… 84%: ํ–ฅํ›„ ์„ธ๋ฌด ๊ณต๊ฐœ ํ™•๋Œ€ ์˜ˆ์ƒ)
  • As regulations increase, compliance costs are rising significantly.(๊ทœ์ • ์ฆ๊ฐ€ โ†’ ์ปดํ”Œ๋ผ์ด์–ธ์Šค ๋น„์šฉ ๊ธ‰์ฆ)

โ†’ Key Points(ํ•ต์‹ฌ ํฌ์ธํŠธ)

  • Tax is no longer just a cost, but a management risk.(์„ธ๊ธˆ = ๋‹จ์ˆœ ๋น„์šฉ์ด ์•„๋‹Œ โ€œ๊ฒฝ์˜ ๋ฆฌ์Šคํฌโ€)
  • There is growing adoption of digital and AI-based tax management systems.(๋””์ง€ํ„ธยทAI ๊ธฐ๋ฐ˜ ์„ธ๋ฌด๊ด€๋ฆฌ ์ฆ๊ฐ€)

โ†’ Implications(์‹œ์‚ฌ์ )

  • For companies(๊ธฐ์—…): Strengthening tax organizations and systems is becoming essential.(์„ธ๋ฌด ์กฐ์งยท์‹œ์Šคํ…œ ๊ฐ•ํ™” ํ•„์ˆ˜)
  • For individuals(๊ฐœ์ธ): Overseas investments are increasingly associated with higher tax risks.(ํ•ด์™ธ ํˆฌ์ž โ†’ ์„ธ๊ธˆ ๋ฆฌ์Šคํฌ ์ฆ๊ฐ€)
  • ํ•œ๊ตญ๊ฒฝ์ œ ์„ธ๊ธˆ ๋‰ด์Šค (2026.06)
  • Deloitte ๊ธ€๋กœ๋ฒŒ ์„ธ๋ฌด ์ •์ฑ… ๋ณด๊ณ ์„œ(2026)
  • OECD ๊ธ€๋กœ๋ฒŒ ์ตœ์ €ํ•œ์„ธ(Pillar2) ์ž๋ฃŒ
  • 2026 ์ƒ์†์„ธ ๊ฐœํŽธ ๊ด€๋ จ ์ž๋ฃŒ ์ข…ํ•ฉ

Tags:

newscusTAXISSUSTAXTREANDS๋‰ด์Šค์ฟ ์Šค์„ธ๊ธˆ์ด์Šˆ์„ธ๋ฌด์ด์Šˆ์กฐ์„ธ์ด์Šˆ์กฐ์„ธํŠธ๋ Œ๋“œ
์ž‘์„ฑ์ž

academicus

Follow Me
๋‹ค๋ฅธ ๊ธฐ์‚ฌ
Previous

๋ณดํ˜ธ๋œ ๊ธ€: [์—ฐ๊ตฌ์ผ์ง€ #2_2026์‹ ์ง„์—ฐ๊ตฌ] ์กฐ์„ธ๋ฒ• ์ฒด๊ณ„์˜ ๋ณต์žก์„ฑ ์ธก์ •โˆ™๋ชจ๋‹ˆํ„ฐ๋งโˆ™๊ด€๋ฆฌ_ ๊ฐ•๋ฏผ์กฐ ๊ต์ˆ˜๋‹˜

Next

[์†Œ๋“์„ธ] ๐Ÿ  ๋‹ฌ๋ผ์ง€๋Š” 2์ฑ„ ์ด์ƒ ๊ณ ๊ฐ€์ฃผํƒ ์ž„๋Œ€ ์†Œ๋“์„ธ / ๊ณ ๊ฐ€์ฃผํƒ ๋ณด์œ ์ž ๋ณด์ฆ๊ธˆ ์„ธ๊ธˆ๊ณผ ๋“ฑ๋ก ์ž„๋Œ€์‚ฌ์—…์ž ์„ธ์ œ ํ˜œํƒ ์—ฐ์žฅ / ์ž„๋Œ€์‚ฌ์—…์ž ๋“ฑ๋ก ๋Œ€์ƒ

๋Œ“๊ธ€ ์—†์Œ! ์ฒซ ๋Œ“๊ธ€์„ ๋‚จ๊ฒจ๋ณด์„ธ์š”.

๋‹ต๊ธ€ ๋‚จ๊ธฐ๊ธฐ ์‘๋‹ต ์ทจ์†Œ

์ด๋ฉ”์ผ ์ฃผ์†Œ๋Š” ๊ณต๊ฐœ๋˜์ง€ ์•Š์Šต๋‹ˆ๋‹ค. ํ•„์ˆ˜ ํ•„๋“œ๋Š” *๋กœ ํ‘œ์‹œ๋ฉ๋‹ˆ๋‹ค

Recent Posts

  • [์ „์‚ฐํšŒ๊ณ„์šด์šฉ์‚ฌ] 2๊ธ‰ ์‹œํ—˜์žฅ ํ›„๊ธฐ / ์‹œํ—˜ ์ „ ๋ง‰ํŒ ์ •๋ฆฌ / ๋‹จ๊ธฐ์ทจ๋“
  • ๐Ÿ“ฃ[Academicus] Instargram ์ธ์Šคํƒ€๊ทธ๋žจ ๐Ÿ“ธ ์ฑ„๋„ ๊ฐœ์„ค ์•ˆ๋‚ด
  • ๐Ÿ“ฐ NEWSCUS Tax Issues & Trends โ€“ 2026๋…„ 10์›” 3์ฃผ์ฐจ
  • ๐Ÿ“บ[Academicus YouTube] ์„ธ๋ฌด ์ „๋ฌธ๊ฐ€๋“ค์€ ํ•™์ˆ ๋Œ€ํšŒ์—์„œ ๋ญ˜ ํ• ๊นŒ? ๐Ÿค” | ์„ธ๋ฌดํšŒ๊ณ„ํ•™๊ณผ ์กธ์—…์ƒ๋“ค์˜ ํ•œ๊ตญ์„ธ๋ฌดํ•™ํšŒ ํ˜„์žฅ VLOG
  • ๐Ÿ“ฐ NEWSCUS Tax Issues & Trends โ€“ 2026๋…„ 10์›” 2์ฃผ์ฐจ

Recent Comments

  1. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ academicus
  2. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ academicus
  3. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ Anonymity
  4. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ Anonymity
  5. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ Administrator

Archives

  • 2026๋…„ 10์›”
  • 2026๋…„ 9์›”
  • 2026๋…„ 8์›”
  • 2026๋…„ 7์›”
  • 2026๋…„ 6์›”
Contact(๋ฌธ์˜ํ•˜๊ธฐ)
Terms & Condition(์ด์šฉ์•ฝ๊ด€)
Privacy Policy(๊ฐœ์ธ์ •๋ณด์ฒ˜๋ฆฌ๋ฐฉ์นจ)
Copyright 2026 โ€” ACADEMICUS. All rights reserved.