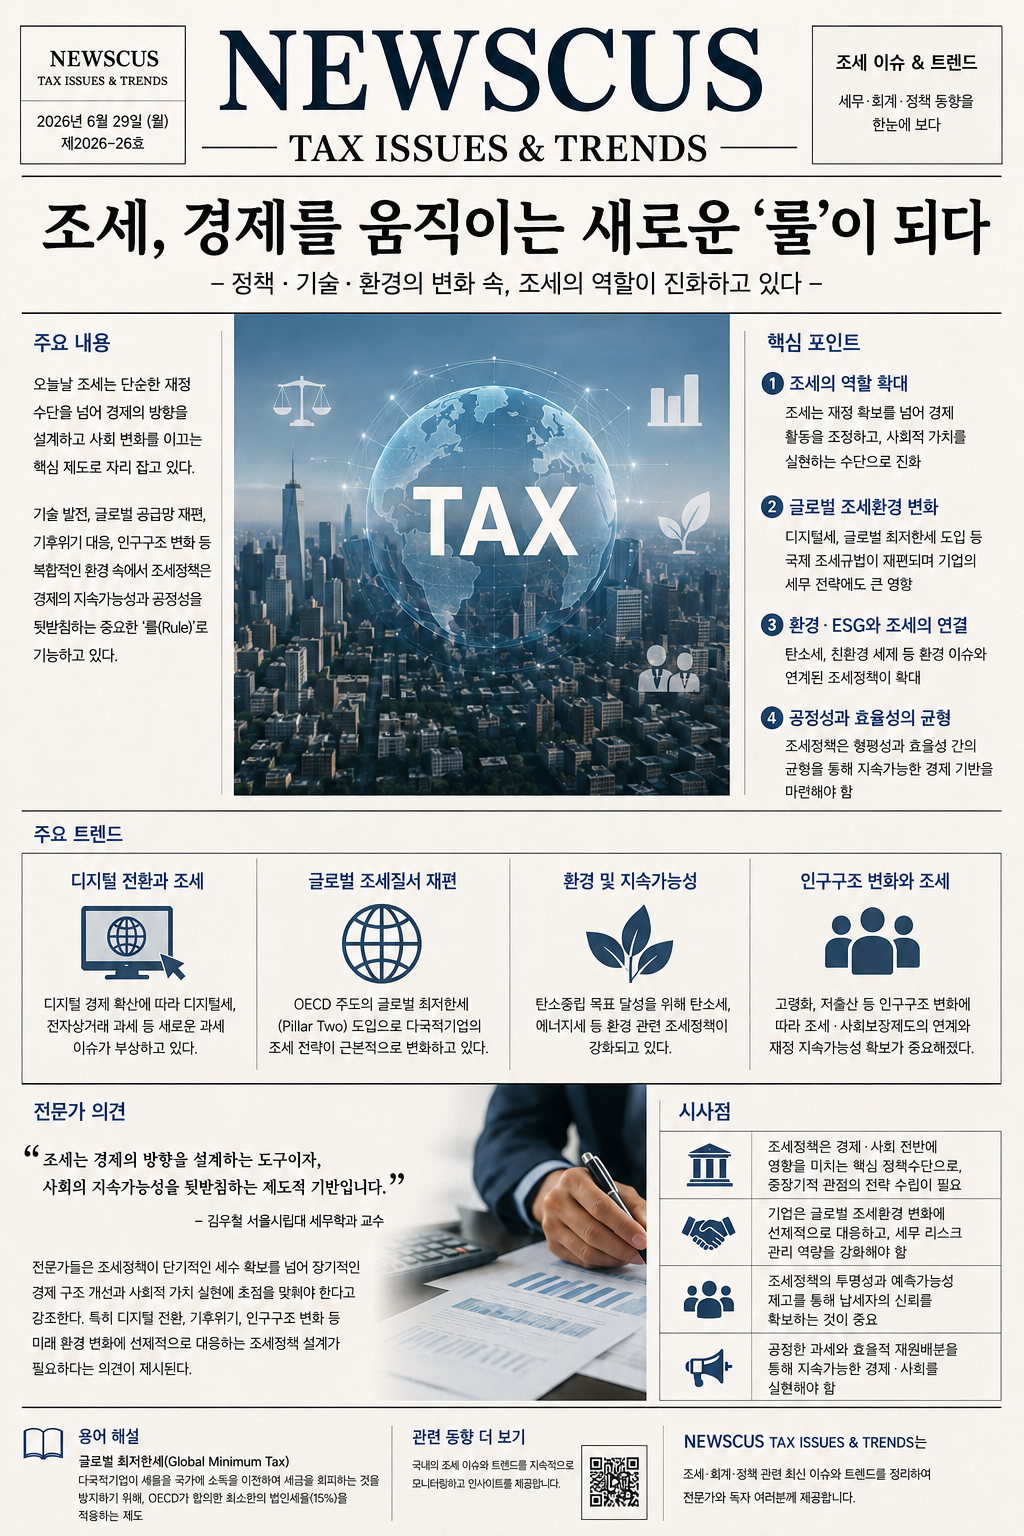
📰 NEWSCUS: Tax Issues & Trends(조세이슈&트렌드) – Taxation Becoming the Rules that Shape the Economy(경제를 설계하는 규칙이 되어가는 조세)

7월 첫째주 조세 이슈 및 트렌드 (국내·해외 종합)


📌 Domestic Tax Issues (Korea)(국내 조세 이슈)
▶ A triple structure of market control (real estate), economic stimulus (investment and households), and fiscal securing (tax increases)
(“시장 통제(부동산) + 경기지원(투자·가계) + 재정확보(증세)”의 3중 구조)
1. Imminent Announcement of the July Tax Reform Plan(7월 세제개편안 발표 임박)
- The government is expected to announce its tax reform plan at the end of July each year(매년 7월 말 정부 세제개편안 발표 예정)
- Currently in the final stage of policy coordination(현재 정책 방향 최종 조율 단계)
- → A period when policy signals are reflected in the market in advance(정책 신호가 시장에 선반영되는 시기)
2. Discussions on Readjusting Real Estate Taxation(부동산 세제 재조정 논의)
- Reviewing an increase in the taxable base for holding taxes (Comprehensive Real Estate Tax)(보유세(종부세) 과세 기준 상향 검토)
- Reconsidering heavier capital gains taxation for multi-home owners(다주택자 양도세 중과 재논의)
- Possibility of strengthened taxation on high-value properties(고가 주택 과세 강화 가능성)
- → A trend toward stronger tax regulations focused on stabilizing the real estate market(부동산 시장 안정 중심의 ‘조세 규제 강화’ 흐름)
3. Changes in Corporate & Investment-Related Taxation(기업 & 투자 관련 세제 변화)
- Partial increase in corporate tax rates (approximately +1 percentage point by bracket)
(법인세 일부 인상(구간별 +1%p 수준)) - Partial reinstatement of the securities transaction tax(증권거래세 일부 환원)
- Discussions on introducing separate taxation for dividend income(배당소득 분리과세 도입 논의)
- → A hybrid strategy balancing investment stimulation and revenue generation(투자 활성화 vs 세수 확보의 혼합 전략)
4. Expansion of Welfare-Oriented Tax Policies(민생·복지형 세제 확대)
- Expansion of tax credits for children and education expenses(자녀·교육비 세액공제 확대)
- Strengthening tax support for childcare and youth(보육·청년 지원 세제 강화)
- → Enhanced response to low birth rates and improved support for real household income(저출산 대응 + 실질소득 보전 기능 강화)
5. Increase in Tax Expenditures(조세지출 증가)
- Tax reductions in 2026 are expected to amount to approximately KRW 80.5 trillion(2026년 감면액 약 80.5조원 규모)
- → Expanded use of tax reductions (tax expenditures) as a policy tool rather than direct taxation(직접 과세보다 세금 감면(조세지출)을 통한 정책 집행 확대)
🌍 Global Tax Issues(해외 조세 이슈)
▶ “Global taxation is shifting from competition to regulation, and from tax avoidance to transparency.”(“글로벌 조세는 경쟁에서 규제로, 절세에서 투명성으로 이동”)
1. Full Implementation of the Global Minimum Corporate Tax (Pillar Two)(글로벌 최저법인세(Pillar 2) 시행 본격화)
- Application of a minimum tax rate of 15%(최소세율 15% 적용)
- Introduction of Qualified Domestic Minimum Top-up Tax (QDMTT) by each country(각국 ‘보충과세(QDMTT)’ 도입)
- → Limiting tax avoidance by multinational enterprises(다국적기업 조세회피 제한)
- → Reduced attractiveness of low-tax jurisdictions(저세율 국가 매력 감소)
- → Shift from international tax competition to a cooperative framework(국제 조세 경쟁 → 협력 구조로 전환)
2. Enhancement of Tax Transparency and Information Exchange(조세 투명성 및 정보교환 강화)
- Expansion of information sharing between countries(국가 간 정보 공유 확대)
- Strengthening regulations on tax evasion and income shifting(탈세·소득 이전 규제 강화)
- → A shift from “hidden taxes” to “transparent taxation”(“숨기는 세금”에서 “보이는 세금”으로 변화)
3. Changes in Global Taxation Trends(글로벌 과세 트렌드 변화)
- Shift from simple tax-cut competition(단순 감세 경쟁) → to an emphasis on fair taxation(공정 과세 강조)
- Expansion of taxation in the digital economy(디지털 경제 과세 확대 흐름)
- Strengthening regulations on multinational enterprises(다국적 기업 규제 강화)
- → The key issue is not tax rates, but securing taxing rights(세율보다 ‘과세권 확보’가 핵심 이슈)
4. Changes in Corporate Tax Strategies(기업 세무 전략 변화)
- Introduction of the global minimum tax(글로벌 최소세 도입) → reduction in traditional tax-saving strategies(절세 전략 축소)
- Need to shift toward structures based on substantive business activities(실질 사업활동 중심 구조로 전환 필요)
- → Transition from “tax avoidance-based strategies” to “substance-based strategies”(‘조세회피 기반 전략 → 실질 중심 전략’ 변화)
- 기획재정부, 「2026년도 조세지출예산서」
- EY Korea, Korea enacts 2026 tax reform bill
- Taxly, 「2026 세제개편안 주요 내용 정리」
- Miraclehub, 「2026년 조세법 개정 주요 내용」
- 네이버 블로그, 「2026년 7월 부동산 세제 개편안 정리」, 「2026년 세제개편안 일정 및 예상 이슈」