๋ณธ๋ฌธ์œผ๋กœ ๊ฑด๋„ˆ๋›ฐ๊ธฐ
-
Subscribe to our newsletter & never miss our best posts. Subscribe Now!
ACADEMICUS
ACADEMICUS
  • About
    • Notice(๊ณต์ง€)
    • Q&A(์งˆ์˜์‘๋‹ต)
    • ACADEMICUS CAMPUS
  • Articles
    • Report
    • Research(์—ฐ๊ตฌ)
      • Reference(์ฐธ๊ณ ์ž๋ฃŒ)
      • Research Journal(์—ฐ๊ตฌ์ผ์ง€)
        • SH๋„์‹œ์—ฐ๊ตฌ์›(2022)
        • Paper Competition(๊ณต๋ชจ์ „)
          • ๊ณต๋ชจ์ „(2022)
          • ๊ณต๋ชจ์ „(2024)
          • ๊ณต๋ชจ์ „(2026)
        • ์‹ ์ง„์—ฐ๊ตฌ์ง€์›์‚ฌ์—…(2026-2029)
          • ์‹ ์ง„์—ฐ๊ตฌ์ง€์›์‚ฌ์—…(2026)
      • Research Report(์—ฐ๊ตฌ ๋ณด๊ณ ์„œ)
    • Languages(์–ดํ•™)
      • TOEIC
      • G-TELP
    • Certificate(์ž๊ฒฉ์ฆ)
      • IT/OA
      • ์žฌ๊ฒฝ๊ด€๋ฆฌ์‚ฌ
      • ๊ธฐ์—…/์„ธ๋ฌดํšŒ๊ณ„
      • ์ „์‚ฐํšŒ๊ณ„์šด์šฉ์‚ฌ
      • ERP ์ •๋ณด๊ด€๋ฆฌ์‚ฌ
      • ์ „์‚ฐ์„ธ๋ฌดํšŒ๊ณ„/AT
      • Tax Accountant(์„ธ๋ฌด์‚ฌ)
        • First examination(1์ฐจ ์‹œํ—˜)
          • Tax law(์„ธ๋ฒ•)
          • Finance(์žฌ์ •ํ•™)
          • Financial accounting(์žฌ๋ฌดํšŒ๊ณ„)
          • Administration Litigation Act(ํ–‰์ •์†Œ์†ก๋ฒ•)
          • Cost management accounting(์›๊ฐ€๊ด€๋ฆฌํšŒ๊ณ„)
        • Final examination(2์ฐจ ์‹œํ—˜)
      • Social Worker(์‚ฌํšŒ๋ณต์ง€์‚ฌ)
    • Field of study(ํ•™๋ฌธ)
      • Tax Law(์กฐ์„ธ๋ฒ•ํ•™)
        • Income Tax(์†Œ๋“์„ธ)
        • Corporate Income Tax(๋ฒ•์ธ์„ธ)
        • Value-Added Tax(๋ถ€๊ฐ€๊ฐ€์น˜์„ธ)
        • Inheritance and Gift Tax Act(์ƒ์†์„ธ ๋ฐ ์ฆ์—ฌ์„ธ๋ฒ•)
        • Restriction of Special Taxation Act(์กฐ์„ธํŠน๋ก€์ œํ•œ๋ฒ•)
        • Framework Act on National Taxes(๊ตญ์„ธ๊ธฐ๋ณธ๋ฒ•)
        • National Tax Collection Act(๊ตญ์„ธ์ง•์ˆ˜๋ฒ•)
        • Local Tax Act(์ง€๋ฐฉ์„ธ๋ฒ•)
        • Comprehensive Real Estate Holding Tax(์ข…ํ•ฉ๋ถ€๋™์‚ฐ์„ธ)
        • Individual Consumption Tax(๊ฐœ๋ณ„์†Œ๋น„์„ธ)
        • Securities Transaction Tax(์ฆ๊ถŒ๊ฑฐ๋ž˜์„ธ)
        • Customs Duty(๊ด€์„ธ)
      • Tax Accounting(์„ธ๋ฌดํšŒ๊ณ„ํ•™)
      • Tax Psychology(์กฐ์„ธ์‹ฌ๋ฆฌํ•™)
    • Practical Work(์‹ค๋ฌด)
      • Tax(์„ธ๋ฌด)
      • Architecture(๊ฑด์ถ•)
  • Review
    • Book(๋„์„œ)
    • Seminar(๊ฐ•์—ฐ/์„ธ๋ฏธ๋‚˜)
    • Paper/Report(๋…ผ๋ฌธ/๋ณด๊ณ ์„œ)
  • Disscussions
  • Resources
    • Form(์–‘์‹)
  • NEWSCUS(AI)
    • Tax issue(์กฐ์„ธ ์ด์Šˆ)
    • Social issue(์‚ฌํšŒ ์ด์Šˆ)
    • Welfare issue(๋ณต์ง€ ์ด์Šˆ)
๋‹ซ๊ธฐ

๊ฒ€์ƒ‰

  • https://www.facebook.com/
  • https://twitter.com/
  • https://t.me/
  • https://www.instagram.com/
  • https://youtube.com/
Subscribe
Tax issue(์กฐ์„ธ ์ด์Šˆ)

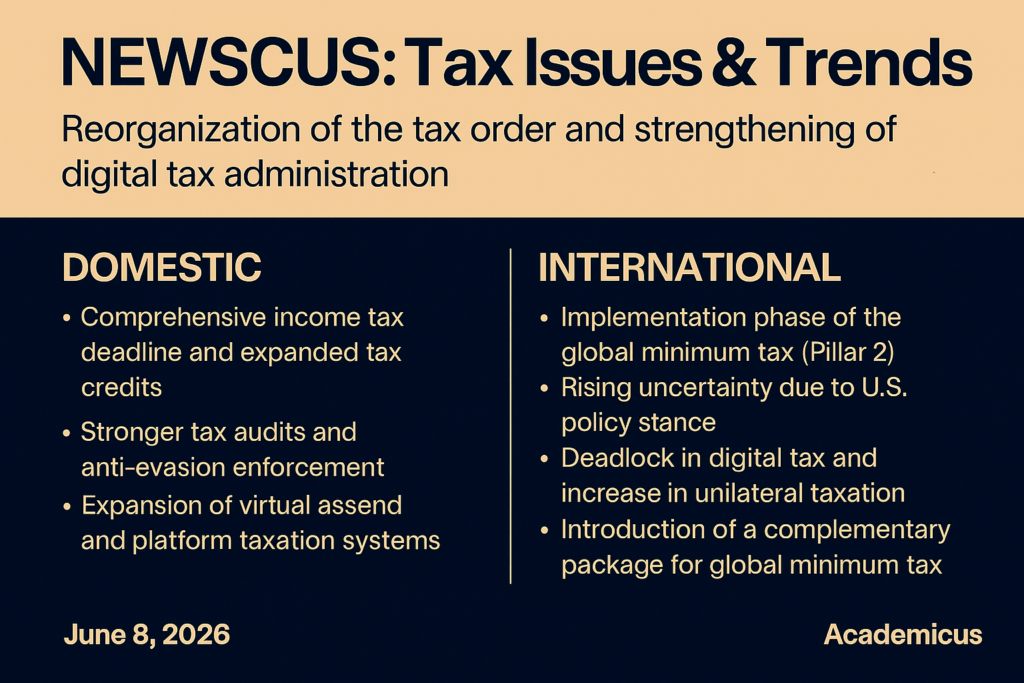
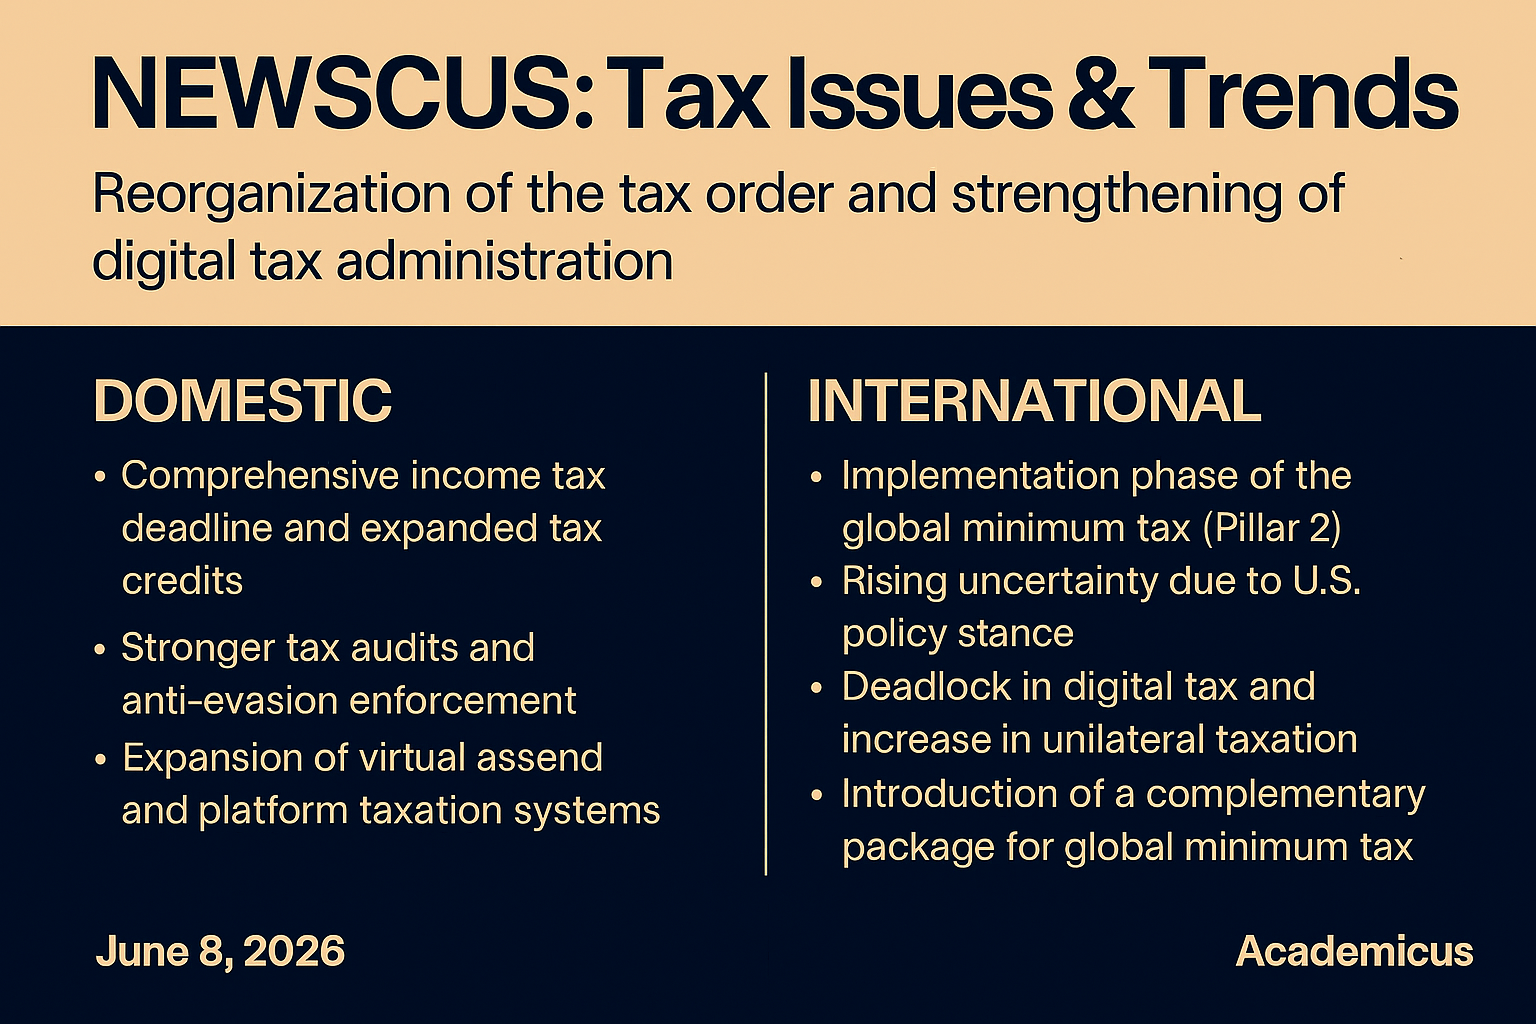
๐Ÿ“ฐ NEWSCUS: Tax Issues & Trends(์กฐ์„ธ์ด์Šˆ&ํŠธ๋ Œ๋“œ) – Reorganization of the tax order and strengthening of digital tax administration(์กฐ์„ธ ์งˆ์„œ ์žฌํŽธ๊ณผ ๋””์ง€ํ„ธ ์„ธ์ • ๊ฐ•ํ™”)

By academicus
2026-06-08 4 Min Read
0

6์›” ๋‘˜์งธ์ฃผ ์กฐ์„ธ ์ด์Šˆ ๋ฐ ํŠธ๋ Œ๋“œ (๊ตญ๋‚ดยทํ•ด์™ธ ์ข…ํ•ฉ)

๐Ÿ“Œ Domestic Tax Issues (Korea)(๊ตญ๋‚ด ์กฐ์„ธ ์ด์Šˆ)

1. Key Tax Event in June(6์›” ํ•ต์‹ฌ ์„ธ๋ฌด ์ด๋ฒคํŠธ): End of Comprehensive Income Tax Filing(์ข…ํ•ฉ์†Œ๋“์„ธ ์‹ ๊ณ  ์ข…๋ฃŒ)

  • Filing deadline for 2025 comprehensive income tax(2025 ๊ท€์† ์ข…์†Œ์„ธ ์‹ ๊ณ  ๋งˆ๊ฐ): June 1(6์›” 1์ผ)
  • Payment deadline for taxpayers subject to enhanced reporting June 30(์„ฑ์‹ค์‹ ๊ณ  ๋Œ€์ƒ์ž๋Š” 6์›” 30์ผ๊นŒ์ง€ ๋‚ฉ๋ถ€)

โ–ถ Key Features(ํŠน์ง•)

  • Expanded tax credits, including child, rent, and marriage deductions(์ž๋…€ยท์›”์„ธยทํ˜ผ์ธ ์„ธ์•ก๊ณต์ œ ๋“ฑ ํ™•๋Œ€ ์ ์šฉ)
  • Noticeable shift in tax burden structure for sole proprietors and freelancers(๊ฐœ์ธ์‚ฌ์—…์žยทํ”„๋ฆฌ๋žœ์„œ ์„ธ๋ถ€๋‹ด ๊ตฌ์กฐ ๋ณ€ํ™” ์ฒด๊ฐ)

2. National Tax Service Policy(๊ตญ์„ธ์ฒญ ์ •์ฑ…): Strengthening Tax Audits & Tax Evasion Response(์„ธ๋ฌด์กฐ์‚ฌ & ํƒˆ์„ธ ๋Œ€์‘ ๊ฐ•ํ™”)

  • Intensive investigations into tax evasion, including the private use of corporate vehicles(๋ฒ•์ธ ์ฐจ๋Ÿ‰ ์‚ฌ์  ์‚ฌ์šฉ ๋“ฑ ํƒˆ์„ธ ์ง‘์ค‘ ์กฐ์‚ฌ)
  • Expansion of the High-Value Tax Delinquent Management Task Force (approx. 10,000 individuals)(๊ณ ์•ก ์ฒด๋‚ฉ๊ด€๋ฆฌ๋‹จ(1๋งŒ๋ช… ๊ทœ๋ชจ) ์šด์˜ ๊ฐ•ํ™”)

โ–ถ Trends(ํŠธ๋ Œ๋“œ)

  • Simultaneous response to โ€œeveryday, close-to-home tax evasion + high-net-worth asset tax evasionโ€(โ€œ์ƒํ™œ๋ฐ€์ฐฉํ˜• ํƒˆ์„ธ + ๊ณ ์•ก์ž์‚ฐ ํƒˆ์„ธ ๋™์‹œ ๋Œ€์‘โ€)
  • Expansion of data-driven tax audits(๋ฐ์ดํ„ฐ ๊ธฐ๋ฐ˜ ์„ธ๋ฌด์กฐ์‚ฌ ํ™•๋Œ€)

3. Strengthening Taxation Infrastructure for Virtual Assets & Platforms(๊ฐ€์ƒ์ž์‚ฐยทํ”Œ๋žซํผ ๊ณผ์„ธ ์ธํ”„๋ผ ๊ฐ•ํ™”)

  • June tax schedule(6์›” ์„ธ๋ฌด์ผ์ •): Includes mandatory submission of virtual asset transaction statements(๊ฐ€์ƒ์ž์‚ฐ ๊ฑฐ๋ž˜๋ช…์„ธ์„œ ์ œ์ถœ ์˜๋ฌดํ™” ํฌํ•จ)

โ–ถ Implications(์˜ํ–ฅ)

  • Entering a full-scale phase of building a taxation system for digital assets(๋””์ง€ํ„ธ ์ž์‚ฐ ๊ณผ์„ธ ์ฒด๊ณ„ ๋ณธ๊ฒฉ ๊ตฌ์ถ• ๋‹จ๊ณ„)
  • Accumulating data to support future expansion of taxation(ํ–ฅํ›„ ๊ณผ์„ธ ํ™•๋Œ€ ๊ธฐ๋ฐ˜ ๋ฐ์ดํ„ฐ ์ถ•์  ์ค‘)

4. Full Implementation of the 2026 Tax Reform Effects(2026 ์„ธ๋ฒ• ๊ฐœ์ • ํšจ๊ณผ ๋ณธ๊ฒฉ ๋ฐ˜์˜)

  • Corporate tax rate increased by 1 percentage point(๋ฒ•์ธ์„ธ์œจ 1%p ์ธ์ƒ) โ†’ rising corporate burden(๊ธฐ์—… ๋ถ€๋‹ด ์ฆ๊ฐ€)
  • Meanwhile(๋Œ€์‹ ):
    • Expansion of tax exemption for childcare allowances(๋ณด์œก์ˆ˜๋‹น ๋น„๊ณผ์„ธ ํ™•๋Œ€)
    • Relaxation of post-management for employment tax credits(๊ณ ์šฉ์„ธ์•ก๊ณต์ œ ์‚ฌํ›„๊ด€๋ฆฌ ์™„ํ™”)
    • Expansion of tax support for start-up SMEs(์ฐฝ์—…์ค‘์†Œ๊ธฐ์—… ์„ธ์ œ ์ง€์› ํ™•๋Œ€)

โ–ถ โ€œStronger corporate taxation + expanded support for individuals and householdsโ€(โ€œ๊ธฐ์—… ๊ณผ์„ธ ๊ฐ•ํ™” + ๊ฐœ์ธ/๊ฐ€๊ณ„ ์ง€์› ํ™•๋Œ€โ€)


5. Easing and Increasing Flexibility of Real Estate & Financial Taxation(๋ถ€๋™์‚ฐยท๊ธˆ์œต ์„ธ์ œ ์™„ํ™” + ์œ ์—ฐํ™”)

  • Extension of exclusion from heavy capital gains tax for multi-homeowners(์–‘๋„์„ธ ์ค‘๊ณผ ๋ฐฐ์ œ ์—ฐ์žฅ (๋‹ค์ฃผํƒ์ž))
  • Introduction of separate taxation for high-dividend stocks(๊ณ ๋ฐฐ๋‹น ์ฃผ์‹ ๋ถ„๋ฆฌ๊ณผ์„ธ ๋„์ž…)

โ–ถ Implications(์˜ํ–ฅ)

  • Stabilization of the real estate market(๋ถ€๋™์‚ฐ ์‹œ์žฅ ์•ˆ์ •)
  • Encouragement of investment in capital markets(์ž๋ณธ์‹œ์žฅ ํˆฌ์ž ์œ ๋„)

6. Transformation of Tax Administration Infrastructure (Digitalization & Expanded Obligations)(์„ธ์ • ์ธํ”„๋ผ ๋ณ€ํ™” (๋””์ง€ํ„ธํ™” & ์˜๋ฌด ํ™•๋Œ€))

  • Full mandatory implementation of electronic tax invoices(์ „์ž์„ธ๊ธˆ๊ณ„์‚ฐ์„œ ์ „๋ฉด ์˜๋ฌดํ™”)
  • Shortened filing deadlines & expanded data submission requirements(์‹ ๊ณ ๊ธฐํ•œ ๋‹จ์ถ• & ๋ฐ์ดํ„ฐ ์ œ์ถœ ํ™•๋Œ€)

โ–ถ Trend(ํŠธ๋ Œ๋“œ)

  • Tax administration evolving into a system of โ€œdigital + real-time managementโ€(์„ธ๋ฌด ํ–‰์ • = โ€œ๋””์ง€ํ„ธ + ์‹ค์‹œ๊ฐ„ ๊ด€๋ฆฌโ€ ์ฒด๊ณ„)

๐ŸŒ Global Tax Issues(ํ•ด์™ธ ์กฐ์„ธ ์ด์Šˆ)

1. Entry into the Implementation Phase of the Global Minimum Tax (Pillar Two)(๊ธ€๋กœ๋ฒŒ ์ตœ์ €ํ•œ์„ธ(Pillar 2) ์‹คํ–‰ ๋‹จ๊ณ„ ์ง„์ž…)

  • In May 2026, the OECD released the Consolidated Commentary on the GloBE Model Rules(OECD๋Š” 2026๋…„ 5์›” “GloBE ๋ชจ๋ธ ๊ทœ์น™ ํ†ตํ•ฉ ํ•ด์„ค์„œ(Consolidated Commentary)”๋ฅผ ๋ฐœํ‘œ)
    โ†’ Provides guidelines for consistent interpretation and implementation across jurisdictions(๊ฐ๊ตญ์ด ๋™์ผ ๊ธฐ์ค€์œผ๋กœ ํ•ด์„ยท์ง‘ํ–‰ํ•˜๋„๋ก ๊ฐ€์ด๋“œ๋ผ์ธ ์ œ๊ณต)
  • Maintenance of the 15% effective tax rate, with clarification of details such as the application of IIR, UTPR, and QDMTT(์‹คํšจ์„ธ์œจ 15% ์œ ์ง€, IIRยทUTPRยทQDMTT ์ ์šฉ ๋ฐฉ์‹ ๋“ฑ ์„ธ๋ถ€์‚ฌํ•ญ ๋ช…ํ™•ํ™”)

โ–ถ Implications(์˜ํ–ฅ)

  • Transition from โ€œagreement โ†’ implementation โ†’ refinementโ€(โ€œํ•ฉ์˜ โ†’ ์‹คํ–‰ โ†’ ์ •๊ตํ™” ๋‹จ๊ณ„โ€๋กœ ์ „ํ™˜)
  • For multinational enterprises, the key task shifts from country-by-country tax rates to managing the overall effective tax rate at the group level(๊ธ€๋กœ๋ฒŒ ๊ธฐ์—…์€ ๊ตญ๊ฐ€๋ณ„ ์„ธ์œจ์ด ์•„๋‹ˆ๋ผ โ€œ๊ทธ๋ฃน ์ „์ฒด ์œ ํšจ์„ธ์œจ ๊ด€๋ฆฌโ€๊ฐ€ ํ•ต์‹ฌ ๊ณผ์ œ)

2. U.S. Factor(๋ฏธ๊ตญ ๋ณ€์ˆ˜) โ†’ Increasing Uncertainty in the International Tax Order(๊ตญ์ œ์กฐ์„ธ ์งˆ์„œ ๋ถˆํ™•์‹ค์„ฑ ํ™•๋Œ€)

  • The United States has pursued an independent approach in digital tax and global minimum tax negotiations(๋ฏธ๊ตญ์€ ๋””์ง€ํ„ธ์„ธยท์ตœ์ €ํ•œ์„ธ ํ˜‘์ƒ์—์„œ ๋…์ž ๋…ธ์„ ) โ†’ emergence of partial exemption structures(์ผ๋ถ€ ๋ฉด์ œ(์˜ˆ์™ธ) ๊ตฌ์กฐ ๋“ฑ์žฅ)
  • The G7 is also moving toward agreements that allow exceptions for U.S. companies(G7๋„ ๋ฏธ๊ตญ ๊ธฐ์—…์— ์˜ˆ์™ธ๋ฅผ ์ธ์ •ํ•˜๋Š” ๋ฐฉํ–ฅ ํ•ฉ์˜ ์›€์ง์ž„)

โ–ถ ๊ฒฐ๊ณผ

  • ๊ธ€๋กœ๋ฒŒ ์ตœ์ €ํ•œ์„ธ โ€œ์™„์ „ ํ†ต์ผโ€ โ†’ โ€œ๊ตญ๊ฐ€๋ณ„ ๋ณ€ํ˜• ์ ์šฉโ€์œผ๋กœ ๋ณ€์งˆ ๊ฐ€๋Šฅ
  • ์กฐ์„ธ ์ฃผ๊ถŒ(sovereignty) vs ๊ตญ์ œ ๊ณต์กฐ ์ถฉ๋Œ ํ™•๋Œ€

3. ๋””์ง€ํ„ธ์„ธ(Pillar 1) ๊ต์ฐฉ + ๊ฐœ๋ณ„ ๊ตญ๊ฐ€ ํ™•๋Œ€

  • Pillar 1(๊ณผ์„ธ๊ถŒ ์žฌ๋ฐฐ๋ถ„)์€ ์—ฌ์ „ํžˆ ์ง€์—ฐ
  • ์บ๋‚˜๋‹คยท์œ ๋Ÿฝ ๋“ฑ์€ ๋…์ž ๋””์ง€ํ„ธ์„œ๋น„์Šค์„ธ(DST) ํ™•๋Œ€ ์‹œ๋„

โ–ถ Outcome(๊ฒฐ๊ณผ)

  • Delay in multilateral negotiations(๋‹ค์ž ํ˜‘์ƒ ์ง€์—ฐ) โ†’ increase in unilateral tax measures by individual countries(๊ตญ๊ฐ€๋ณ„ unilateral tax ์ฆ๊ฐ€) โ†’ continued risk of trade disputes and retaliatory tariffs(๋ฌด์—ญ๋ถ„์Ÿ ๋ฐ ๋ณด๋ณต๊ด€์„ธ ๋ฆฌ์Šคํฌ ์ง€์†)

4. Introduction of a โ€œComplementary Packageโ€ for the Global Minimum Tax(๊ธ€๋กœ๋ฒŒ ์ตœ์ €ํ•œ์„ธ โ€˜๋ณด์™„ ํŒจํ‚ค์ง€โ€™ ๋„์ž…)

  • From 2026, the OECD(OECD๋Š” 2026๋…„๋ถ€ํ„ฐ)
    • Recognizes real investment incentives(์‹ค๋ฌผํˆฌ์ž ์ธ์„ผํ‹ฐ๋ธŒ ์ธ์ •)
    • Expands safe harbour provisions(Safe harbour ํ™•๋Œ€)
    • Introduces a side-by-side taxation system

โ–ถ Key Change(ํ•ต์‹ฌ ๋ณ€ํ™”)

  • Shift from strengthening simple taxation(๋‹จ์ˆœ ๊ณผ์„ธ ๊ฐ•ํ™”) โ†’ to a more flexible system that considers investment attraction(ํˆฌ์ž ์œ ์น˜ ๊ณ ๋ คํ•œ ์œ ์—ฐํ•œ ์ œ๋„๋กœ ๋ณ€ํ™”)

5. Structural Changes in Corporate Tax Policy (OECD Report)(๋ฒ•์ธ์„ธ ์ •์ฑ…์˜ ๊ตฌ์กฐ ๋ณ€ํ™” (OECD ๋ณด๊ณ ์„œ))

  • Emphasis on the impact of corporate taxation on the business ecosystem
  • In particular(ํŠนํžˆ):
    • High compliance costs(๋†’์€ compliance ๋น„์šฉ) โ†’ hinder entry of startups(์Šคํƒ€ํŠธ์—… ์ง„์ž… ์ €ํ•ด)
    • Tax incentives(์„ธ์ œ ์ธ์„ผํ‹ฐ๋ธŒ) โ†’ may lead to bias toward large corporations(๋Œ€๊ธฐ์—… ํŽธ์ค‘ ๊ฐ€๋Šฅ์„ฑ)

โ–ถ Trend Summary(ํŠธ๋ Œ๋“œ ์š”์•ฝ)

  • Shift from โ€œtax rate competitionโ€(โ€œ์„ธ์œจ ๊ฒฝ์Ÿโ€) โ†’ to โ€œpolicy design centered on market structure and innovation impactโ€(โ€œ์‹œ์žฅ ๊ตฌ์กฐยทํ˜์‹  ์˜ํ–ฅ ์ค‘์‹ฌ์˜ ์ •์ฑ… ์„ค๊ณ„โ€)
  • Google News. (2026). ๋Œ€ํ•œ๋ฏผ๊ตญ ์ตœ์‹  ๋‰ด์Šค.
  • SBS ๋‰ด์Šค. (2026). ์ด์Šˆ ๋ฉ”์ธ.
  • ๋‰ด์ŠคํŽŒํ”„. (2026). 2026๋…„ ์ •์น˜ยท์‚ฌํšŒ ์ด์Šˆ ์ด์ •๋ฆฌ.
  • ๊ตญ๋ฏผํ†ตํ•ฉ์œ„์›ํšŒ. (2026). 5๋Œ€ ์‚ฌํšŒ๊ฐˆ๋“ฑ ์ฃผ์š” ์ด์Šˆ ๋ถ„์„ ๊ฒฐ๊ณผ ๋ฐœํ‘œ.
  • World Economic Forum. (2026). Global Risks Report 2026.
  • International Monetary Fund (IMF). (2026). World Economic Outlook, April 2026.
  • United Nations News. (2026). AIโ€™s environmental costs threaten water, land and climate.
  • Encyclopaedia Britannica. (2026). Major Events of 2026.

์ž‘์„ฑ์ž

academicus

Follow Me
๋‹ค๋ฅธ ๊ธฐ์‚ฌ
Previous

๐Ÿงพ ๋ถ€๋ถ€๊ฐ„ ์ž๊ธˆ๊ฑฐ๋ž˜์— ๋Œ€ํ•œ ์ฆ์—ฌ์„ธ ๊ณผ์„ธ์˜ ๋ฌธ์ œ์ ๊ณผ ๊ฐœ์„ ๋ฐฉ์•ˆ: ๋Œ€๋ฒ•์› 2015.9.10. ์„ ๊ณ  2015๋‘41937 ํŒ๊ฒฐ์„ ์ค‘์‹ฌ์œผ๋กœ(Problems and Reform Measures in the Taxation of Gift Tax on Financial Transactions Between Spouses)_2024_ํ•œ๊ตญ์„ธ๋ฌดํ•™ํšŒ_๊ฐ•๋ฏผ์กฐ, ์šฐ์šฉ์ƒ

Next

๐Ÿงพ ์†Œ๋“์„ธ์œจ๊ตฌ์กฐ์™€ ๋ณต์ง€์ •์ฑ…์— ๋Œ€ํ•œ ํƒœ๋„๊ฐ€ ์ฝ”๋กœ๋‚˜19 ๊ฒฝ์ œ์ง€์›์ •์ฑ… ํ‰๊ฐ€์— ๋ฏธ์นœ ์˜ํ–ฅ(The Impact of Income Tax Rate Structure and Attitudes toward Welfare Policies on the Evaluation of COVID-19 Economic Support Policies)_2024_ํ•œ๊ตญ์กฐ์„ธ์—ฐ๊ตฌ์†Œ_๊ฐ•๋ฏผ์กฐ, ์‹ ์˜ํšจ

๋Œ“๊ธ€ ์—†์Œ! ์ฒซ ๋Œ“๊ธ€์„ ๋‚จ๊ฒจ๋ณด์„ธ์š”.

๋‹ต๊ธ€ ๋‚จ๊ธฐ๊ธฐ ์‘๋‹ต ์ทจ์†Œ

์ด๋ฉ”์ผ ์ฃผ์†Œ๋Š” ๊ณต๊ฐœ๋˜์ง€ ์•Š์Šต๋‹ˆ๋‹ค. ํ•„์ˆ˜ ํ•„๋“œ๋Š” *๋กœ ํ‘œ์‹œ๋ฉ๋‹ˆ๋‹ค

Recent Posts

  • [์ „์‚ฐํšŒ๊ณ„์šด์šฉ์‚ฌ] 2๊ธ‰ ์‹œํ—˜์žฅ ํ›„๊ธฐ / ์‹œํ—˜ ์ „ ๋ง‰ํŒ ์ •๋ฆฌ / ๋‹จ๊ธฐ์ทจ๋“
  • ๐Ÿ“ฃ[Academicus] Instargram ์ธ์Šคํƒ€๊ทธ๋žจ ๐Ÿ“ธ ์ฑ„๋„ ๊ฐœ์„ค ์•ˆ๋‚ด
  • ๐Ÿ“ฐ NEWSCUS Tax Issues & Trends โ€“ 2026๋…„ 10์›” 3์ฃผ์ฐจ
  • ๐Ÿ“บ[Academicus YouTube] ์„ธ๋ฌด ์ „๋ฌธ๊ฐ€๋“ค์€ ํ•™์ˆ ๋Œ€ํšŒ์—์„œ ๋ญ˜ ํ• ๊นŒ? ๐Ÿค” | ์„ธ๋ฌดํšŒ๊ณ„ํ•™๊ณผ ์กธ์—…์ƒ๋“ค์˜ ํ•œ๊ตญ์„ธ๋ฌดํ•™ํšŒ ํ˜„์žฅ VLOG
  • ๐Ÿ“ฐ NEWSCUS Tax Issues & Trends โ€“ 2026๋…„ 10์›” 2์ฃผ์ฐจ

Recent Comments

  1. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ academicus
  2. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ academicus
  3. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ Anonymity
  4. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ Anonymity
  5. ๐Ÿ“ฃ[Academicus] ํšŒ์›๊ฐ€์ž… ๋ฐ ํŽ˜์ด์ง€ ์ฐธ์—ฌ(Subscribe) ๋ฐฉ๋ฒ• ์•ˆ๋‚ด์˜ Administrator

Archives

  • 2026๋…„ 10์›”
  • 2026๋…„ 9์›”
  • 2026๋…„ 8์›”
  • 2026๋…„ 7์›”
  • 2026๋…„ 6์›”
Contact(๋ฌธ์˜ํ•˜๊ธฐ)
Terms & Condition(์ด์šฉ์•ฝ๊ด€)
Privacy Policy(๊ฐœ์ธ์ •๋ณด์ฒ˜๋ฆฌ๋ฐฉ์นจ)
Copyright 2026 โ€” ACADEMICUS. All rights reserved.